The Global Debt Trap: Borrowing More, Receiving Less
For many developing countries, borrowing money is supposed to support economic growth, finance infrastructure and improve living standards. Governments take loans to build roads, expand electricity networks, strengthen healthcare and invest in education.
But an increasingly difficult financial situation is emerging: some countries are paying more in debt repayments and interest than they receive through fresh borrowing.
This creates a cycle in which governments borrow to meet existing obligations, pay high interest rates and struggle to find enough money for development.
According to the World Bank’s International Debt Report 2026, low- and middle-income countries paid approximately $436 billion more in external debt service than they received in new financing between 2022 and 2025.
Although long-term debt flows turned positive again in 2025, the cumulative outflow highlights the financial pressure many developing economies continue to face.
What Does It Mean to Pay More Than You Borrow?
When a government borrows money, it agrees to repay the principal along with interest over an agreed period.
For example, imagine a country borrows $100 million. Over several years, it may have to repay the original $100 million plus $40 million in interest.
Its total repayment becomes $140 million.
The situation becomes more difficult when the country cannot generate enough revenue to meet these obligations. It may need to borrow again, sometimes at higher interest rates, simply to manage existing repayments.
This is how debt can become a recurring financial burden rather than a source of development.
It is important to distinguish between total lifetime repayments and annual net financing. A country paying more in debt service than it receives in new loans during a particular period does not automatically mean it has repaid more than its original borrowing over its entire history.
Developing Countries Face Record Debt Costs
The World Bank reported that the external debt of developing countries reached a record $9.4 trillion in 2025, representing a 5.5% increase from the previous year.
Low- and middle-income countries paid approximately $1.4 trillion in principal and interest during 2025, marking the fifth consecutive annual increase.
The pressure is particularly severe for countries eligible for concessional financing through the World Bank’s International Development Association.
These countries paid an average interest rate of 8.2% on new private-creditor commitments in 2025, the highest level since 1989. New bond issues carried an average rate of 9.4%.
These figures show that access to international borrowing does not necessarily mean affordable financing.
Why Do Poorer Countries Pay Higher Interest Rates?
Several factors contribute to the higher borrowing costs faced by developing economies.
1. Higher Perceived Financial Risk
International lenders assess a country’s ability to repay its debt. Countries with unstable currencies, limited foreign-exchange reserves, political uncertainty or weak public finances may be considered riskier borrowers.
To compensate for this perceived risk, lenders demand higher interest rates.
2. Currency Depreciation
Many developing countries borrow in US dollars or other foreign currencies while collecting most government revenue in their domestic currencies.
If the local currency loses value, repaying foreign-currency debt becomes more expensive.
For example, a government that owes $1 billion will need more domestic currency to repay the same dollar amount if its currency depreciates.
3. Dependence on Private Creditors
Private lenders and international bond investors often charge more than multilateral development institutions.
When affordable financing becomes difficult to obtain, governments may turn to commercial loans or international bond markets with higher interest costs.
4. Refinancing Existing Debt
Governments sometimes issue new bonds or borrow additional money to repay loans that are reaching maturity.
This can prevent an immediate default, but it may not reduce the total debt burden. If new borrowing carries a higher interest rate, the country’s future repayment obligations can increase.
How Debt Payments Affect Healthcare and Education
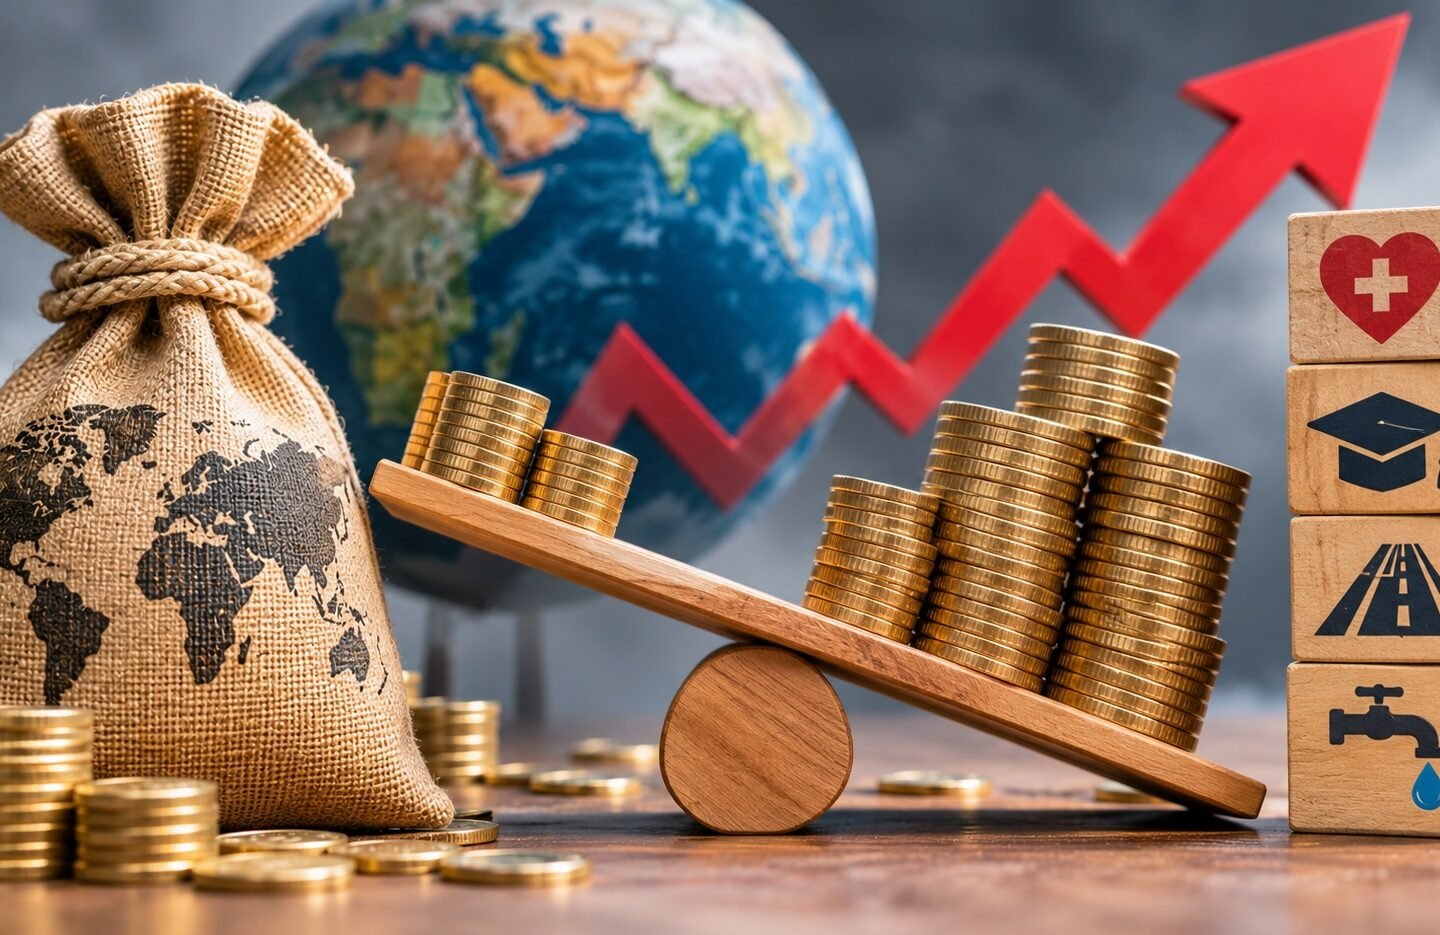
Debt servicing is not just a financial issue. It directly affects the resources governments can allocate to public services.
UN Trade and Development (UNCTAD) reported in its 2026 analysis that approximately 3.7 billion people live in countries where public-debt interest payments exceed spending on health or education.
Developing countries paid nearly $1 trillion in net interest on public debt in 2025, almost three times the amount recorded in 2010.
When governments spend a growing share of their revenue on interest, fewer resources may remain for:
- Building hospitals and improving healthcare facilities.
- Recruiting teachers and expanding schools.
- Developing roads, bridges and transport networks.
- Improving electricity and water infrastructure.
- Supporting employment and social welfare programmes.
- Investing in climate resilience and disaster preparedness.
This creates a long-term development challenge because countries need investment to grow, but expensive debt can restrict their ability to make those investments.
The Role of the World Bank and IMF
International institutions such as the World Bank and the International Monetary Fund play an important role in supporting countries facing financial difficulties.
They provide financing, technical assistance and economic policy guidance.
The World Bank also offers concessional financing to eligible low-income countries through IDA, which provides grants and loans on more favourable terms than many commercial lenders.
The IMF can provide emergency financial support and assistance to countries experiencing balance-of-payments problems.
However, financial support often comes with economic conditions, debt-management requirements or policy reforms. Governments must balance these requirements with their domestic economic and social priorities.
Why Debt Restructuring Matters
When a country cannot meet its repayment obligations, it may negotiate with creditors to restructure its debt.
Debt restructuring can involve:
- Extending repayment deadlines.
- Reducing interest rates.
- Negotiating a reduction in the principal amount.
- Providing temporary repayment relief.
- Replacing expensive loans with more affordable financing.
The objective is to make debt manageable and prevent a financial crisis from becoming worse.
However, negotiations can be complicated when a country owes money to multiple creditors, including governments, international institutions, banks and private bondholders.
Different creditors may have different priorities, making a coordinated solution difficult.
Is the Situation Improving?
There are some signs of improvement, but the overall picture remains mixed.
The World Bank reported that long-term net debt transfers to low- and middle-income countries turned positive in 2025, reversing a $118.4 billion outflow in 2024 into a $45.4 billion inflow.
This means new long-term financing exceeded debt-service payments in that category during 2025.
However, the cumulative outflow between 2022 and 2025 remained substantial. Debt stocks also continued to rise, and borrowing costs for the poorest countries remained elevated.
The improvement in financing flows therefore does not mean that developing economies have escaped their debt pressures.
What Needs to Change?
Economists and international organisations have highlighted several areas where improvements could help reduce the burden:
- Greater access to affordable, long-term development financing.
- More transparent and efficient debt restructuring.
- Stronger domestic revenue collection and public financial management.
- Better management of foreign-exchange risks.
- More predictable international development assistance.
- Greater coordination between governments, private creditors and multilateral institutions.
The challenge is not simply to stop countries from borrowing. Developing economies need investment to build infrastructure, create jobs and improve living standards.
The key issue is whether borrowing generates enough long-term economic value to justify its financial cost.